THE total GB contract floorcoverings market increased by an estimated 1.5% in 2025 to 49.9m sq m, following declines of 2.3% in 2023 and 1.3% in 2024. Further modest growth is expected, with the market forecast to increase by 0.9% in 2026 and 1.4% in 2027.
These are among the findings from the latest edition of The Contract Floorcovering Market in Great Britain – The Palmer Flooring Report, published by Leading Edge and now available.
The report provides a detailed assessment of the GB contract floorcoverings market, examining changes in market size, product mix and end-use sectors alongside manufacturer performance, brand recognition and preference.
SUBHEAD: Performance by product
While the overall market returned to growth in 2025, performance continues to vary considerably between flooring types.
LVT remains one of the most significant areas of change within the contract flooring market. Its longer-term growth has altered the product mix considerably over successive editions of the report, with LVT competing across an increasingly broad range of contract applications. However, as the category has matured, the rate of growth has moderated.
Carpet tile experienced a difficult period during 2023 and 2024, but the latest research points to an improvement in 2025. Manufacturer and distributor evidence also suggests a more positive picture going forward, although the category continues to face competition from LVT and other hard flooring products.
Carpet roll remains affected by the longer-term shift towards alternative flooring types in some applications, although there are signs that the market has become more stable following several years of decline.
The picture for resilient flooring is more mixed. Resilient sheet remains an important part of the contract market, particularly within health, education and other institutional applications, while changes within resilient tile reflect both underlying sector demand and continuing shifts in product choice.
The report also examines the smaller product sectors including seamless resin, ceramic, wood and laminate, where market trends can differ significantly from those experienced by the larger flooring categories.
SUBHEAD: Changing fortunes across building sectors
Construction activity remains an important influence on flooring demand, but the latest research highlights considerable differences between individual end-use sectors.
Offices remain the largest individual sector for contract floorcoverings and are particularly important for carpet tile. However, the sector continues to adjust to changing patterns of workplace use and investment.
Health and education remain important sources of flooring demand, particularly for resilient products, while retail, leisure, housing and other public and private sectors have followed different patterns over the period.
As a result, the return to overall market growth in 2025 does not represent a uniform recovery. Individual flooring manufacturers continue to experience quite different market conditions depending on the products they supply and the sectors in which they are strongest.
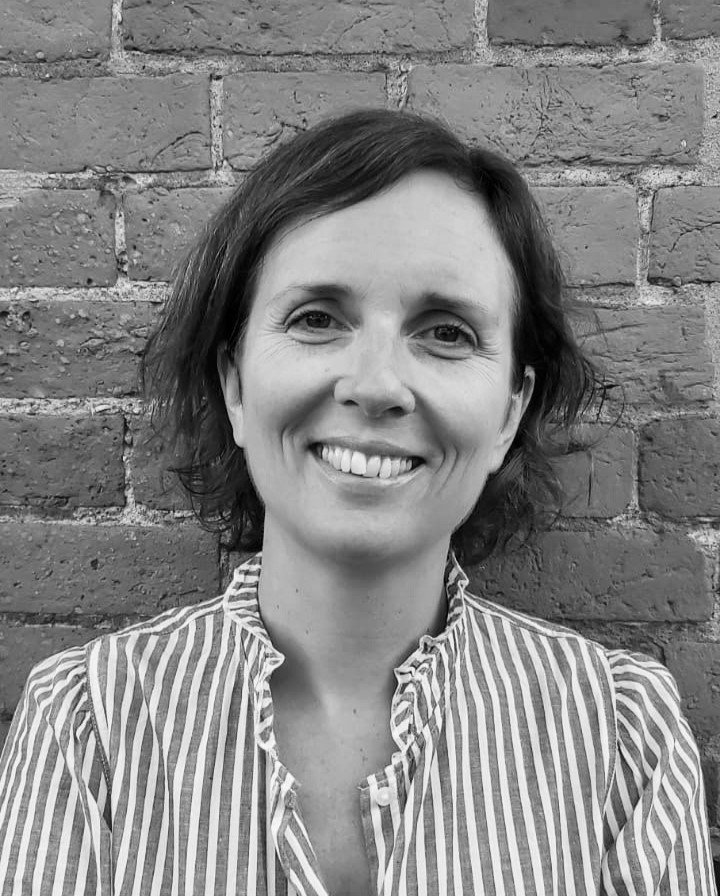
Elly Cousin, director at Leading Edge, comments: ‘The return to growth in 2025 is encouraging following two years of market decline, but there are still significant differences beneath the headline figure.
‘Product substitution continues to reshape the market, while the fortunes of individual flooring types remain closely linked to activity across their key end-use sectors.’
SUBHEAD: Preferred suppliers and brand recognition
The 2026 research also highlights changes in the competitive landscape for carpet tile and resilient flooring manufacturers.
Polyflor retains its position as the most preferred resilient flooring manufacturer amongst both specifiers and contractors. Within carpet tile, there has been more movement since the previous research, with Forbo Tessera moving into first place for preference among specifiers, while Burmatex is the most preferred manufacturer among contractors.
The research also examines manufacturer recognition and performance across nine individual attributes, including decorative appearance, product quality, product range, technical support, sales representation, product availability, competitive price, overall service and sustainability. The findings highlight differences between the views of specifiers and contractors, as well as changes in manufacturer performance since the previous research.
SUBHEAD: The Contract Floorcovering Market in Great Britain 2026
The 2026 report draws on an extensive programme of primary research with flooring contractors, architects and specifiers, specialist contractors, manufacturers, suppliers and distributors. This is combined with confidential manufacturer sales information, construction-sector data, extensive desk research and Leading Edge’s historical market data.
The report is published in three volumes, covering market size and trends by product and end-use sector; manufacturer recognition, preference and ratings; and detailed verbatim feedback from across the industry.
The Contract Floorcovering Market in Great Britain – The Palmer Flooring Report 2026 is now available from Leading Edge.
01252 279 990
CAPTION: Elly Cousin